

Despite the prevailing assumption that economic policy exists to fix markets, correct failures, patch inefficiencies, and generally take a step back, every so often a reminder appears that market-shaping is not only possible, but already underway in different parts of the world.
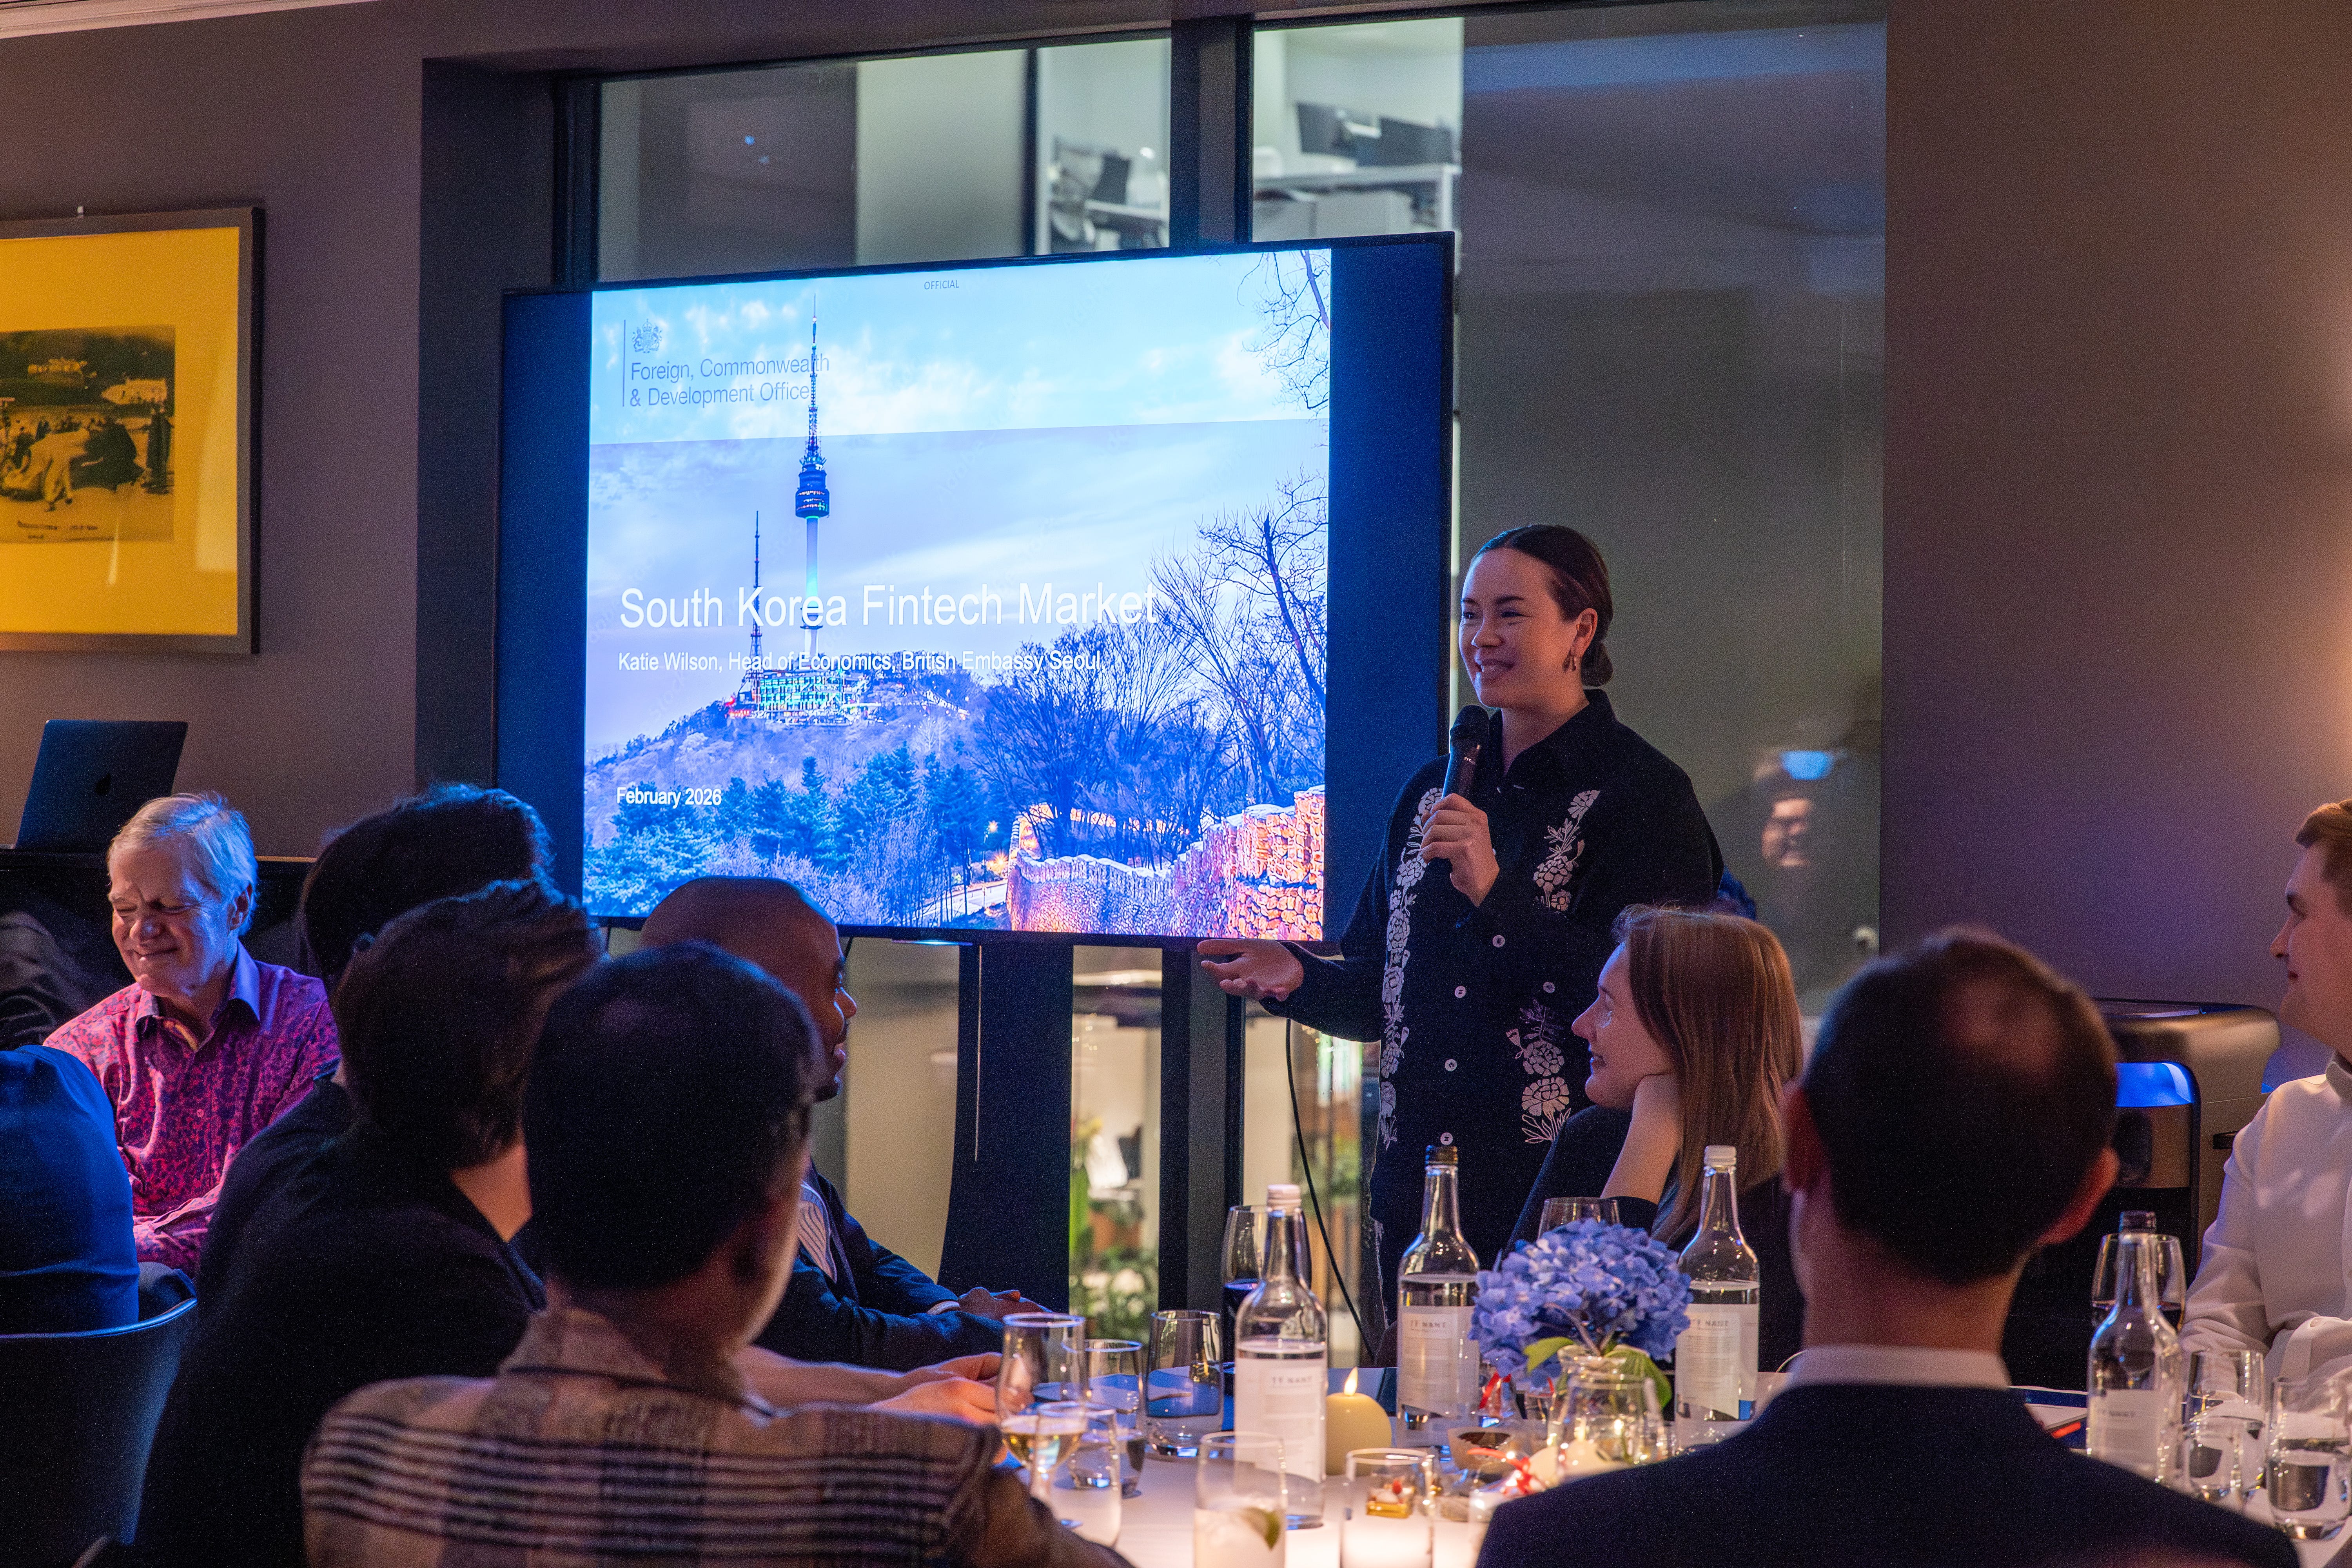
Last night I was invited to attend a FinTech UK & Korea event hosted by the British Embassy in Seoul and Co-Labs Global. South Korea – one of the world’s fastest-growing fintech markets with 39 million open-banking users, a rapidly maturing digital infrastructure in the form of MyData, and a clear ambition to become a world-leading fintech economy – offers a compelling example of institutional intent in practice: setting direction, building shared infrastructure, and structuring the terms on which private actors participate.
For South Korea, their fintech story is framed less as one of sectoral encouragement and more as the intentional shaping of conditions for interoperability, trust, and experimentation. Security expectations are being treated as a foundation of legitimacy rather than a compliance afterthought. Shared rails are then standardised, so innovation builds on common infrastructure rather than parallel systems. This, in turn, enables regulatory sandboxes to institutionalise experimentation within the perimeter of the state itself. In combination, these moves signal that growth is not being left to chance; it is being actively shaped and played with.
This closely resembles what development institutions increasingly describe as digital public infrastructure – shared, interoperable rails upon which private innovation can build which interestingly, as David Eaves argues, raises all sorts of real thick strategic questions of not simply whether a country adopts digital public infrastructure, but what kind of tech stack it chooses to commodify and govern – and what that implies for sovereignty, competition, and long-term value capture.
This stands in contrast to the UK’s more familiar posture, where technology policy often defaults to “push incentives”: funding early innovation, lowering costs, and waiting for markets to consolidate around the value created. The recurring outcome is that public infrastructure absorbs systemic risk while private actors capture the majority of scale-driven returns. The issue is not that these investments are misguided or wasted., it is that the terms of partnership are rarely designed with sufficient intentionality or conditionality to ensure that public risk is matched by public reward. And, over time, this produces a pattern in which the state carries early uncertainty while long-term value accrues elsewhere. The architecture of partnership, rather than the volume of investment, becomes the central design flaw.
I think these comparisons are meaningful for many reasons. Market failure theory – the intellectual foundation of most Western industrial policy – asks governments to intervene only where markets fall short, then return to the sidelines. It is a static technocratic framework, oriented toward optimising what already exists. Market-shaping, by contrast, begins with a different question: what kind of market do we want to build, who are the willing actors, and what institutional capacities are required to steer it there?
These questions imply that public support need not be blind to outcomes. Conditional mechanisms – whether linked to domestic investment, knowledge sharing or interoperability standards – can ensure that public risk is matched by public return. Without such design, partnership defaults to asymmetry (Read more from Marianna Mazucato and Dani Rodik here)
Which is why the more interesting question, watching Korea’s pitch, wasn’t how many British firms might enter the market. It was whether the partnership terms being offered would actually align private activity with the infrastructural outcomes Korea is trying to build. Market access and market co-creation are not the same thing. Who carries the cost of building the field? Who benefits when it scales? These questions don’t answer themselves – their solutions (the conditionality of these relationships) have to be designed.
Interestingly enough, the UK has shown it can do this quite well. The antimicrobial subscription model introduced by NICE and NHS England is a quiet example of genuine policy creativity. Rather than paying pharmaceutical companies per pill sold – which would have created the wrong incentives entirely – the NHS pays a fixed annual fee based on a drug’s assessed value to the health system. Revenue is delinked from volume, and private incentives are realigned with long-term public benefit. The whole mechanism was redesigned, not just the funding level.
While Fintech isn’t antibiotics, the underlying question is the same: can you design the terms of partnership so that private capability serves public infrastructure outcomes, rather than just extracting value from them? Could partnership models reward improvements in interoperability or system security, not just transaction volume? Could data-sharing frameworks be built to reduce lock-in rather than entrench it?
These are the design questions that separate a high-growth sector from something more durable – infrastructure whose governance shapes the economy over the long term.
Korea is making a credible case that it knows what kind of fintech market it wants to build. The invitation to British firms is real. But the quieter provocation is for the UK to ask the same question of itself – not just how to grow the sector, but how to govern it in a way that actually captures public value from the infrastructure we’re already building.
More broadly, the strategic question for governments is not whether markets will form, but which layers of the stack they choose to shape, commodify, and govern — and fintech is not exempt from that logic. The capacity exists. The question is whether it is exercised with the same degree of intentionality in the digital financial infrastructure now emerging.
"it is being actively shaped and played with."
and thats a different definition of government leadership that we are used to, but you describe how it is essential.